Malta’s special tax residence framework is being consolidated from 1st January 2027 through the implementation of Legal Notice 195 of 2026. The four current categories of special tax status will be unified under a single programme, known as the Individual Tax Programme Rules (the ‘Programme’). Whilst the preferential 15% tax rate on qualifying foreign income remains unchanged, the Programme introduces more demanding financial and administrative requirements.
The New Statuses:
Under the Programme, the current categories of beneficiaries will be renamed as the following statuses:

Who is Affected:
The new rules will apply to new applications under the Individual Tax Programme submitted on or after the 1st January 2027. Beneficiaries already benefitting under the current programmes, as well as new applicants who QUALIFY under the terms of the current programmes and APPLY by the 31st December 2026, will remain subject to the current programme rules until the 31st December 2031 (the transitory period).
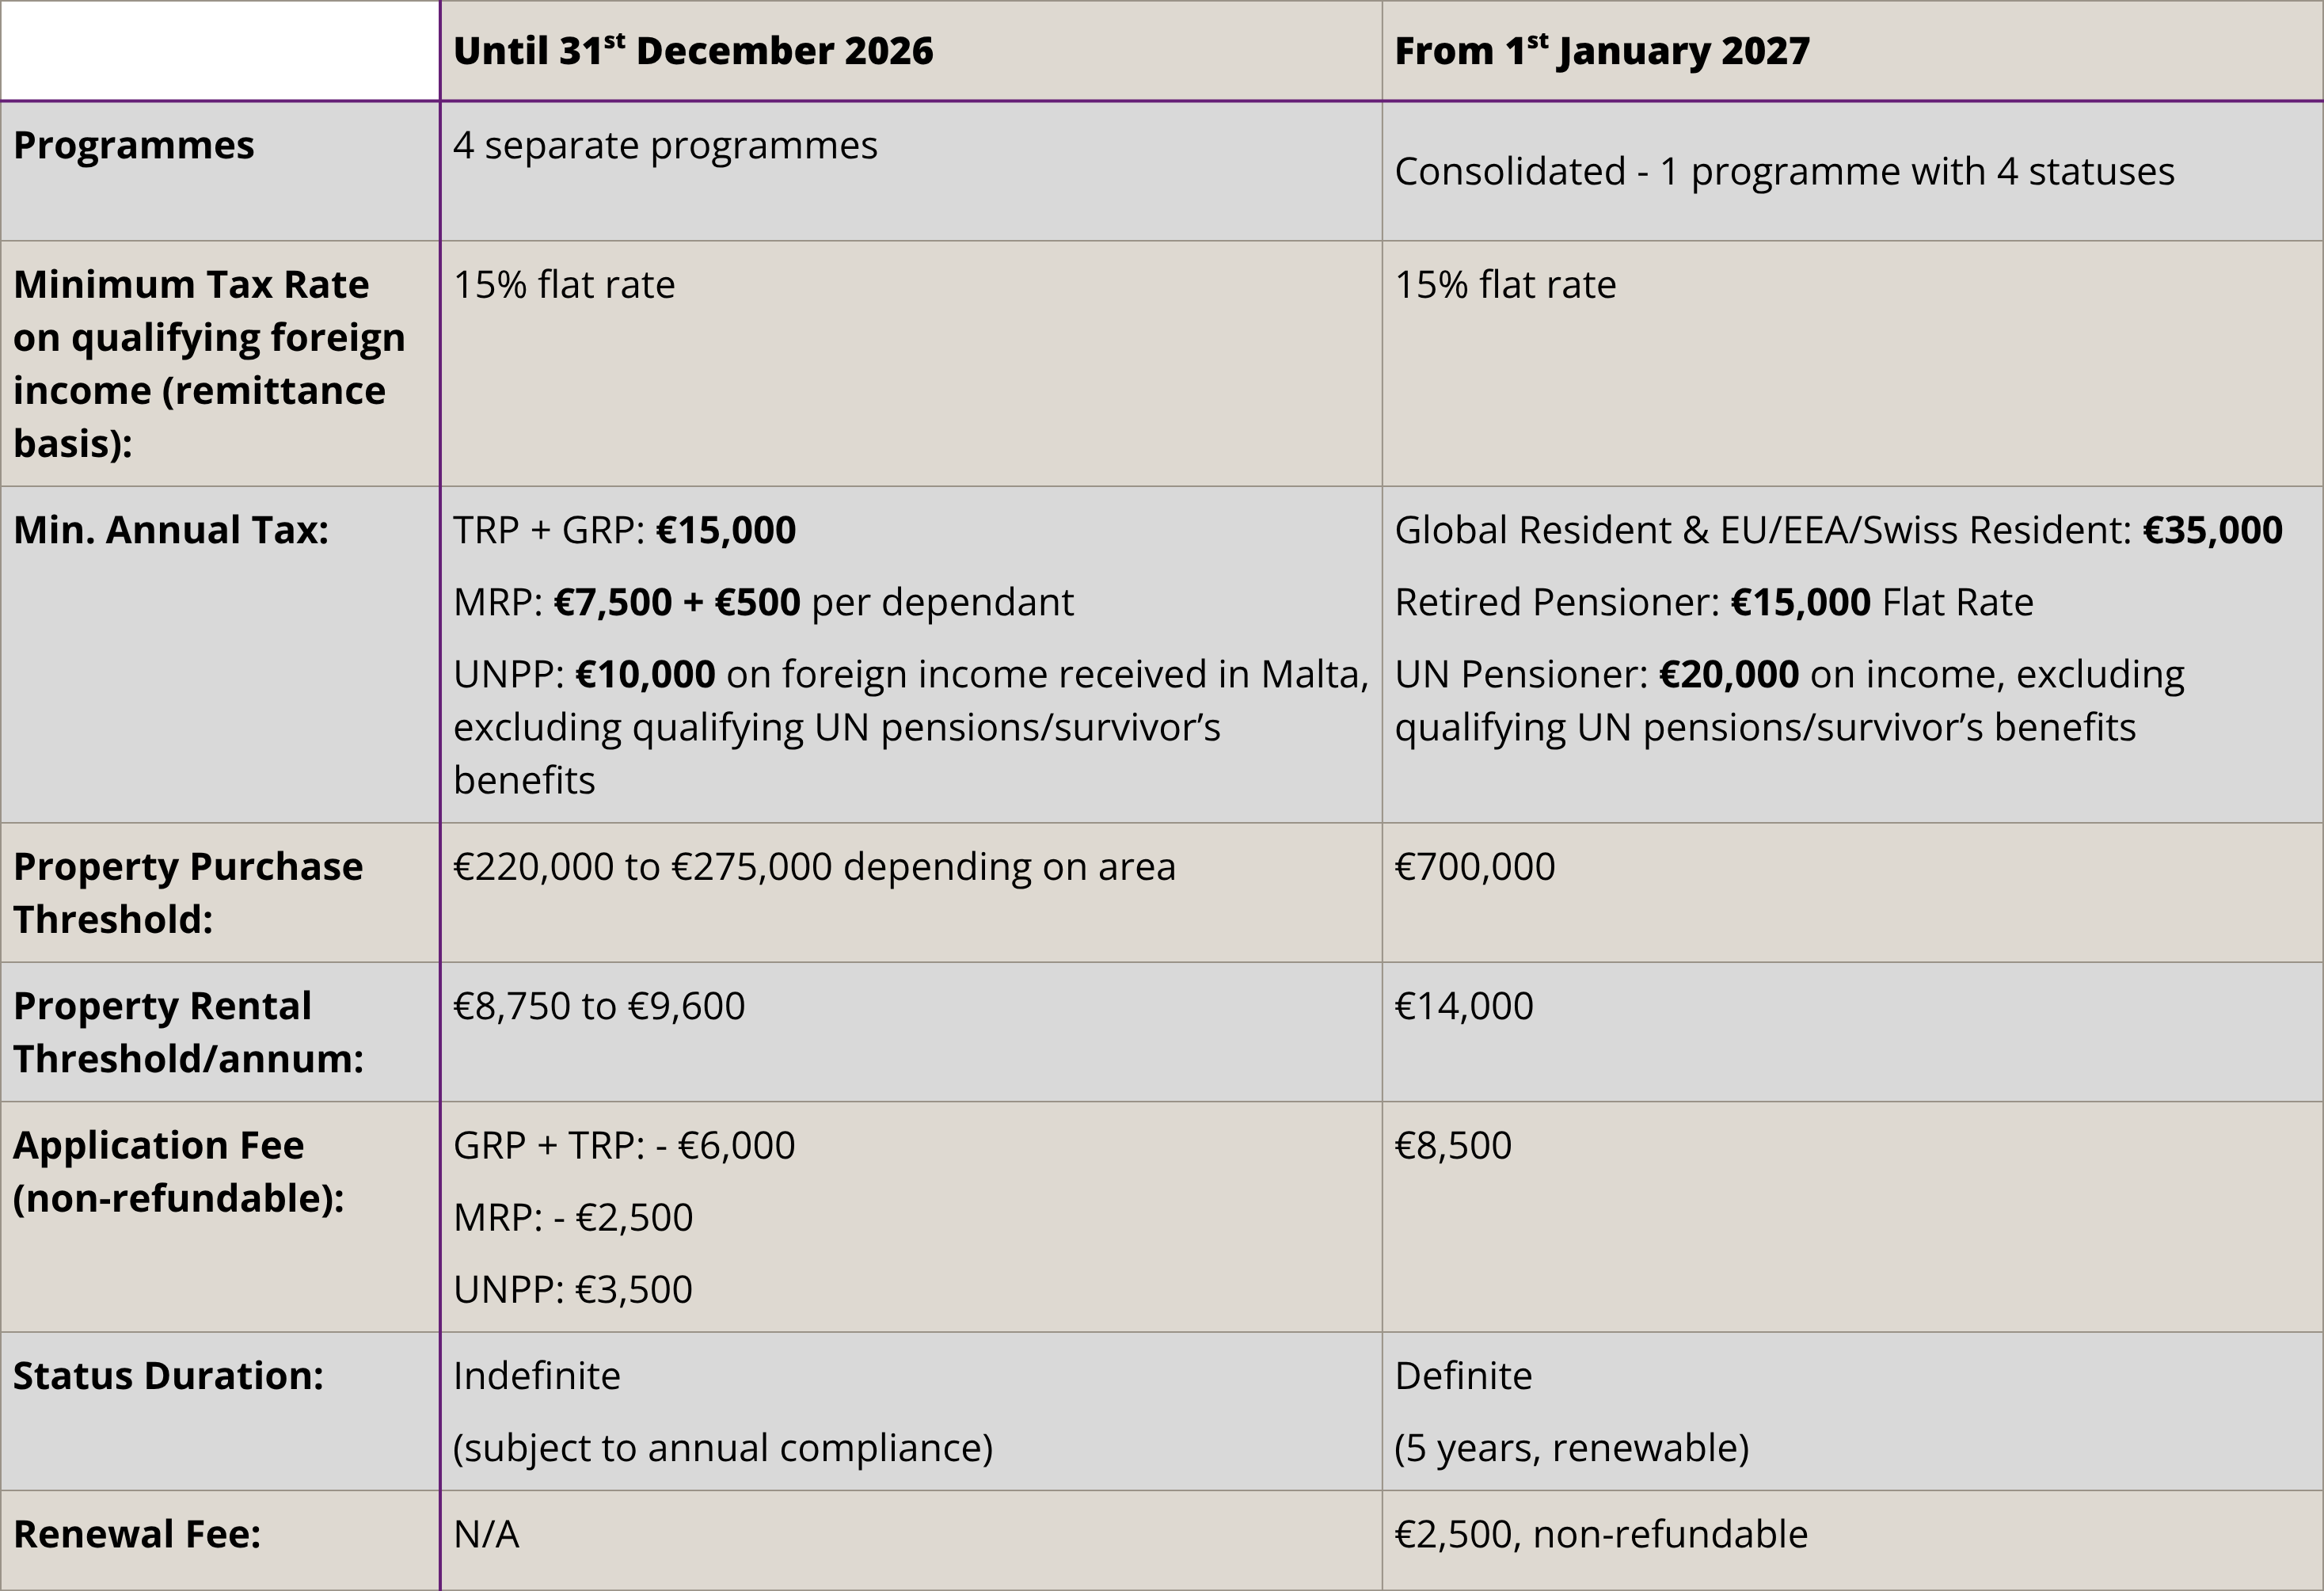
- →Minimum annual tax increases from €15,000 to €35,000 – translating into €20,000 more tax per annum for Global Resident or EU/EEA/Swiss Resident tax statuses
- →Minimum annual tax increases from €7,500 to €15,000 – translating into double the current minimum annual tax paid by Retired Pensioner applicants;
- →Higher property acquisition and rental thresholds;
- →A change from indefinite to a definite five-year status, renewable for further five-year periods subject to conditions;
- →Higher application fees;
- →Introduction of a €2,500 non-refundable renewal fee that was previously not applicable.
Tighter and new qualifying conditions will be introduced by the Programme which incude earlier submissions for annual tax compliance declarations and a narrower definition of 'dependants'.

Why you should apply now:
If you are already in the process of relocating to Malta; meet the current TRP or GRP property and income thresholds; or if you are a pensioner who pays less then the new flat rate of €15,000 under the MRP rules, then you should consider applying before the 31st December 2026 deadline.
In this way you will benefit from the current rules and defer being subject to the new thresholds till after 31st December 2031.
How we can Help
At Phoenix Wise Solutions, we can assess your eligibility under the current programmes as well as assist with the application process and the annual compliance requirements. Besides providing advisory and support services, we are also able to assist with other ancillary assistance necessary to fulfil the different requirements of the programmes.
Dr. Stephan Gauci
Founder & Managing Director
Dr. Melanie Schembri
External Consultant